Showing posts with label Condo. Show all posts
Tuesday, July 15, 2014
BLOSSOMING IN VIC PARK
Proposed downtown condo project will include apple orchard
BY DYLAN ROBERTSON
CALGARY HERALD JULY 15, 2014
Fresh apples will be ripening between two downtown condominium towers as a developer aims to give Calgary a more fruitful and dynamic city centre.
The Orchard on Twelfth is a two-tower project at the southeast corner of 12th Avenue and 5th Street S.E., just northeast of Stampede Park. Lamb Development Corp. of Toronto is planning two 31-storey buildings, which will nestle a one-acre orchard of apple trees between them on a 61,000-square-foot land parcel.
“Not only is this a public and private amenity for the city, but also a true green feature; not a stupid green roof that really in the end doesn’t do much,” said company head Brad Lamb. “It’s a phenomenal thing to have in a city, and it’s going to produce tens of thousands of apples which are going to be eaten.”
The company commissioned an Ipsos Reid survey last month which polled 1,000 Americans and 1,000 Canadians, asking them to guess the location from a digital rendering of the project with its apple orchard. Most Canadians thought the image was in Vancouver or Toronto, placing Calgary seventh out of 13 possibilities; Americans thought of Portland or New York and placed Calgary 12th.
The same poll found that 93 per cent of North Americans — especially younger adults — want greener downtowns, and would welcome projects that delivered food.
“I always try to deliver, if I can, a public amenity that the city will enjoy and the residents will enjoy,” Lamb said, comparing the Orchard on Twelth with another property his corporation is developing, 6th and Tenth, which will include a fountain park. “Our cities aren’t green enough, visually and for taking in C02.”
Richard Cho, senior market analyst with Canada Mortgage and Housing Corp., says the projects are part of an ongoing build up in new Calgary condominiums.
“We had lower inventory and now we see that being made up for,” said Cho. He noted that in last year’s January to June period, construction started for only 1,004 apartments. In the same months this year, the city netted some 4,010 starting units, and Cho says more are anticipated.
Alberta isn’t known for its apple orchards but Lamb said an agricultural firm has chosen tree species that can grow edible fruit in the area. A third party will be paid to prune the trees and harvest the fruit for sale or donation.
But for Lamb, the buildings themselves are more interesting.
“They’re rectangular, simple in design, but they’re super clean and super modern,” he said. “We’re delivering beautiful architecture and affordable apartments; these two buildings are spectacular in their own right.”
Units will range from $249,900 for one-bedroom apartments to over a million dollars for larger units. Lamb says those prices are competitive with Beltline properties. The project will cost $130 million with $170 million in expected revenue, he said.
An older house on the block will be demolished, while buildings on the fifth of the block not owned by Lamb Development will remain in place.
Lamb says his company is currently waiting for a permit, but he expects ground to be broken within the year as no zoning exception is needed. He expects the first phase to open in about three and a half years, followed by the second about five years from now.
Labels:
Calgary,
Condo,
Development,
Lamb Development Corp.,
The Orchard,
Victoria Park,
YYC,
YYCRealEstate
Tuesday, November 5, 2013
ASK NOW!
It never hurts to ask and check before buying
BY SHELL BUSEY
THE PROVINCE NOVEMBER 3, 2013
If you are looking to purchase a strata unit in a building that has not yet been built, there are some things regarding the layout of your potential suite you should be aware of.
You want to be aware of backto-back bedrooms and the level of soundproofing in the walls. This is something that is expensive - if not impossible - to change later.
One suggestion for anyone looking for a new condo or townhouse or resale unit: if you can gain access to next door or above or below suites, take a radio with you and play it in the adjoining suite. You may be amazed at how music can transfer through walls.
Also, are the strata rules and regulations in place, or is the strata formed yet? Rules and regulations can limit parking, guest parking, pets, smoking and age of residents. Keep in mind your first purchase may be the biggest capital investment you will make and you do not want it to be negative.
One question I am asked many times at seminars, home shows and in phone calls is: "How do you tell the best from the worst when buying your first piece of real estate?"
I am aware of buyers using the services of home inspectors, but that does not mean they are going to find some of the most important downsides to your potential home.
If you are looking at an apartment, old or new, you may want to monitor the building over a period of 24 hours, or better yet, a week.
For example, how many shift workers live in the building, possible smokers or even rowdies who have no respect for their neighbours? If a condo building is in an area undergoing revitalization, there may be developments under consideration that could take away views that you enjoy.
A number of the points can be important in a new singlefamily homes subdivision, as well. Due to zoning bylaws, homes can be built close to one another. Keep the following items in mind when you are house hunting. Is the property a bare-land strata, at what height can you have a fence or hedge, and are storage sheds allowed? What is the maximum allowable size of sun decks, should you want to enlarge yours? Is there outdoor play equipment such as basketball hoops and trampolines, and is there a goodneighbour policy with regards to noisy heat pumps and air conditioning compressors?
Last, but not least, consider your budget - not just for mortgage payments but yearly costs to operate the home.
You would be surprised how many homebuyers do not properly prepare and end up getting into a costly scenario.
For more home-improvement information or to send Shell an email go to www.askShell. com and become a member of Shell's HouseSmart club.
Labels:
Buying,
Condo,
inspection,
Music,
parking,
Pets,
Question,
Real Estate,
smoking,
soundproofing,
strata,
unit,
walls
Friday, October 11, 2013
HIGH IN THE SKY APPLE PIE
Calgary condo market booming with high sales growth
New condo sales at strongest levels since 2006
BY MARIO TONEGUZZI
CALGARY HERALD OCTOBER 11, 2013
CALGARY — The pace of year-over-year sales growth in the resale condo market is much higher than the single-family home market this year in Calgary.
And new condo sales are also moving in an upward trend towards the strongest levels since 2006.
“Calgary’s condominium market remains resilient and in high demand with new construction being well supported demographically, exhibiting steady sales throughout the inner city and the downtown core,” said Kaitlyn Gottlieb, a realtor with Century 21 Bamber Realty Ltd. in Calgary.
“Calgary’s luxury condominium market remains immensely sought after. As Calgarians’ incomes continue to rise and our business sector attracts relocations, high-end buyers are taking advantage of the luxury condos that Calgary has to offer, boasting high-end finishes and their close proximity to the downtown core.”
According to the Calgary Real Estate Board, year-to-date until October 10, MLS sales in the condo apartment category in the city were 3,253, up 14.58 per cent from the same period a year ago and the average sale price has jumped by 6.14 per cent to $298,050. In the condo townhouse category, sales of 2,600 are up 22.18 per cent from last year and the average sale price has risen by 6.60 per cent to $338,809.
The single-family home market in the city has seen sales rise by 7.36 per cent to 13,482 with the average price moving up by 8.18 per cent to $517,730.
“While the recent floods have undoubtedly impacted all sectors of Calgary’s housing market inclusive of the condominium market, as demonstrated by the increased demand for affordable housing, the overall market remains stable,” said Gottlieb.
“Steady migration, employment and population growth are major contributors as we move into the fourth quarter of the year. The relative affordability of our city’s housing market remains one of the best in Canada and we can expect to see Calgary’s condominium market continue to rise at a moderate, sustainable pace.”
A report by Altus Group says new condo sales in Calgary are at the strongest levels since 2006.
It said the new multi-family condo market has seen impressive sales in the first half of 2013 with almost 3,000 sales to start the year, an increase of 400 sales compared with the same period in 2012.
The sales pace this year is 16 per cent ahead of 2012 at mid-year and 74 per cent better than in 2011 for the same period.
“New suburban apartment and townhouse projects entering the market are primarily responsible for the strong sales results, with mid-year sales up sharply in the north and south quadrants of the city following the launch of several new projects during the Spring,” said the report. “In the downtown region, sales are generally consistent with last year’s pace, although sales activity has been more focused at projects with superior locations and faster possession timing.”
The report said the strong sales so far this year are expected to push the annual sales volume to about 5,000 units, potentially making 2013 the second strongest sales year in the past decade.
“Developers will begin to see cost pressures from higher land prices, construction cost escalations and a declining land supply in the suburban regions, while consumer activity could be impacted by the recent price growth, higher interest rates and more restrictive lending practices,” said the report.
“While home ownership will remain the goal for most consumers, the higher prices and interest rates may force some consumers to delay their purchase decision while they save for a larger down payment.”
Labels:
2006,
2013,
Condo,
Condominium,
Employment,
Growth,
Migration,
Population,
Real Estate,
Sales,
Single-Family,
Strong
Tuesday, October 1, 2013
BATTLING BOARDS
Alberta tries a new tack for resolving condo disputes
By Annalise Klingbeil
Calgary Herald October 1, 2013
A newly created tribunal system will help condominium owners in Alberta who are embroiled in disputes avoid costly and time-consuming legal battles, the Minister of Service Alberta announced on Monday.
Manmeet Bhullar said the new dispute resolution process, expected to be operational by early 2014, will help protect the hundreds of thousands of condominium owners who live in Alberta.
“Everyday, hard-working Albertans who live in a condominium can’t afford $200 or $300 or $500 an hour to pay a lawyer,” Bhullar said Monday, standing near the Bow River, across from several condominium towers.
Bhullar said it’s common for condo owners to disagree with other condo owners and condo boards on issues ranging from parking spots to fees. “Owners can have disputes with one another over things like noise complaints and even odours coming from another unit,” he said.
Bhullar said the new system will allow condo owners to pay a “reasonable fee” to have their matter heard before an adjudicator.
Stephen Cassady, the president of the Canadian Condominium Institute — South Alberta Chapter, welcomed the government’s announcement of a new resolution model.
“It’s an entire waste of resources and time of people who could be better spending it doing something else,” he said of the current system.
Cassady said the industry has changed significantly in the 13 years since the government last updated its condominium legislation in 2000.
“If we can get (disputes) out of the court systems then we will do a phenomenal job of improving everybody’s life,” he said.
The new changes are the first of many to come to the province’s Condominium Property Act, following public consultation with Albertans, Bhullar said.
Instead of waiting for changes to the Act to be tabled in the Legislature in the spring, Bhullar said he is tasking a committee of people, led by Sherwood Park MLA Cathy Olesen, to develop the new dispute resolution model immediately. “Developing a more affordable and speedy way to resolve differences will help protect condominium owners,” Bhullar said.
Bhullar said condominiums accounted for nearly 20 per cent of home sales in Alberta in 2012.
Photo By: mira66
Labels:
Alberta,
Boards,
Calgary,
Condo,
Condominium,
Disputes,
Lawyer,
Legal,
Manmeet Bhullar,
Real Estate,
Resolution
Wednesday, August 28, 2013
CONDO FORECAST FOR 2014
Calgary condo price and sales growth forecast for 2014
Median price hike best in Canada this year
By Mario Toneguzzi
Calgary Herald August 28, 2013
CALGARY — Record growth is not in the foreseeable future of the Canadian condo market, but it is also likely the sector will be able to avoid a major downturn, according to the latest Conference Board of Canada condo report released Wednesday by Genworth Canada.
The Summer 2013 Metropolitan Condo Outlook suggests population growth and employment gains will help maintain demand levels to absorb supply inventory.
Calgary starts will be hampered in the third quarter by the flooding earlier in the year, but as the “youngest” city in the survey, it is expected to enjoy the highest growth in starts and resale volumes in 2014, with price growth at a moderate level of two per cent to 3.5 per cent over the next few years, said the report.
The report forecast the median price for a resale condo apartment in Calgary will rise this year by 2.8 per cent, the highest in Canada, to $251,237 and by another 3.3 per cent in 2014 to $259,640.
However, it is forecasting sales to drop by 11.6 per cent to 3,508 units this year but rebound by 10.2 per cent in 2014 to 3,867 sales.
“Whether it’s first-time homebuyers entering home ownership, empty nesters looking to downsize or professionals seeking a shorter commute, condos appear to remain a popular option for urban Canadians,” said Brian Hurley, chairman and chief executive of Genworth Canada.
The report said economic factors affecting the housing market, such as employment, interest rates and population growth, will only undergo moderate changes. Employment is expected to rise modestly in the medium-term and interest rates are expected to increase gradually, while population expansion and demographics will continue to support demand in regional markets.
“As condo starts near past averages and inventories edge closer to demand, we are seeing the condo market stabilize both in terms of the price of existing units and the volume of new construction,” said Robin Wiebe, senior economist at the Centre for Municipal Studies at the Conference Board of Canada. “Softer prices and positive economic factors continue to make condos an affordable way for Canadians to achieve home ownership.”
The report said condo sales in Calgary had been doing well before the flood, averaging over 3,900 units at an annual rate in the fourth quarter of 2012 and the first quarter of 2013.
“Active apartment listings had tapered off, hovering below 1,000 units in the fourth quarter of last year and the first quarter of 2013,” said the report. Still, for 2012 as a whole, active listings averaged 1,263 units, up 30 per cent from 2011. The flood has presumably damaged at least some actual or potential apartment listings. This will cut active listings in the third quarter by 10 per cent and lead to a 26 per cent decline in listings for all of 2013.
“The lower listings last autumn lifted the sales-to-active-listings ratio slightly above 35 per cent, its highest level since 2009 and likely approaching sellers’ market conditions. The ratio is forecast to stabilize near 34 per cent in the third quarter of 2013 and end the year at 31 per cent. A solidly balanced market featuring a sales-to-active-listings ratio between 33 and 35 per cent is our call for between 2014 and 2017.”
According to the Calgary Real Estate Board, year-to-date until August 27,
there have been 2,767 MLS condo apartment sales in the city, up 14.20 per cent
from a year ago. The median price has risen by 3.60 per cent to $259,000 while
the average sale price has increased by 7.01 per cent to $297,954.
Labels:
2014,
Calgary,
Condo,
Condominium,
Forecast,
Genworth Canada,
Growth,
Outlook,
Real Estate,
Sales
Friday, April 12, 2013
MONDO CONDO
Pace increases for condo sales
By Josh Skapin
Calgary Herald April 11, 2013
Sales of resale condos were on the upswing in March compared to a year earlier, says the Calgary Real Estate Board.
Sales climbed to 630 deals, up 6.6 per cent from 591 transactions during the same month last year.
Townhomes led the charge in sales with 283 moves after 235 units changed hands a year earlier, marking a 20 per cent change.
That came with a 10.3 per cent climb in new listings with 395 after there were 358 last March.
The apartment market, on the other hand, saw little change, easing 2.5 per cent.
“The condominium apartment market remains in balance,” says CREB chief economist Ann-Marie Lurie, in a news release.
Last month 347 apartments were sold after 356 deals during the same time in 2012.
New listings of apartments eased 13 per cent at 560 after there were 644 during the same time last year.
“While it has moved to the lower end of the spectrum, it remains better supplied than the single-family market and the majority of product available is in an affordable price range,” says Lurie.
While condo apartments dipped in sales, the benchmark price went up six per cent. The benchmark price is that of a typical home based on a formula that uses various factors to ensure accurate comparisons.
For condo apartments, the benchmark price was $257,700 last month, up six per cent from $243,000 a year earlier.
The townhome benchmark price also increased last month compared to a year earlier.
It reached $286,800 for a four per cent step up from $274,600 this time in 2012.
Wednesday, March 20, 2013
WORLD'S MOST EXPENSIVE APARTMENT BUILDING
Inside the world’s most expensive apartment building
By: Julie Zeveloff
Business Insider 13/03/15
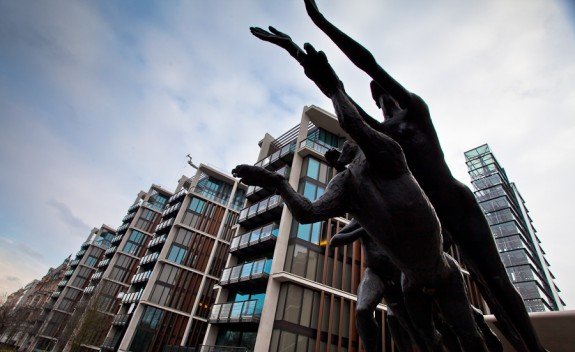
London’s One Hyde Park is one of the wealthiest and most secretive residences in the world.
Apartments in the Knightsbridge complex cost more than $11,000 a square foot, nearly three times the typical price of luxury London real estate.
But relatively little is known about the people who own homes there. Of the 76 apartments sold in the 86-unit building, 64 are registered to corporations and just 17 are listed as primary residences, according to Nicholas Shaxson, who wrote a great exposé of the building in this month’s Vanity Fair.
Even so, Shaxson and others have found out who some of One Hyde Park’s owners are. Get to know some of the sheikhs, oligarchs, and global rich who own apartments at the world’s most expensive apartment building.
One Hyde Park, located in Knightsbridge, is adjacent to Hyde Park and the Mandarin Oriental hotel.
And Rory Carvill, an insurance entrepreneur and chairman of U.K. based R.K. Carvill & Co. Ltd. reportedly paid $33.5 million for his residence and additional storage space.
By: Julie Zeveloff
Business Insider 13/03/15
London’s One Hyde Park is one of the wealthiest and most secretive residences in the world.
Apartments in the Knightsbridge complex cost more than $11,000 a square foot, nearly three times the typical price of luxury London real estate.
But relatively little is known about the people who own homes there. Of the 76 apartments sold in the 86-unit building, 64 are registered to corporations and just 17 are listed as primary residences, according to Nicholas Shaxson, who wrote a great exposé of the building in this month’s Vanity Fair.
Even so, Shaxson and others have found out who some of One Hyde Park’s owners are. Get to know some of the sheikhs, oligarchs, and global rich who own apartments at the world’s most expensive apartment building.
One Hyde Park, located in Knightsbridge, is adjacent to Hyde Park and the Mandarin Oriental hotel.
The per-square-foot price of a unit at One Hyde Park is 10 TIMES the price of average residential real estate in London, and nearly three times more than luxury real estate in the city.
Among other perks, there’s a stainless steel ozone pool, an entertainment suite, a golf simulator, and a spa run by the Mandarin Oriental.
There are also three retailers on site: Rolex, McLaren, and Abu Dhabi Islamic Bank.
Security in the building is insane. There are panic rooms, bulletproof glass, and guards trained by British Special Forces, according to Vanity Fair.
One Hyde Park was created through a joint venture between high-end real estate developers the Candy brothers and Sheikh Hamad bin Jassim bin Jaber Al Thani, the Prime Minister of Qatar.
The owners were some of the first people to buy into the building. The Sheikh paid $64 million for his triplex, which Vanity Fair calls “the best apartment of all.”
Christian Candy reportedly has two apartments that cost $85 million. And Nick Candy owns an 11th-floor duplex penthouse.
In 2010, Ukrainian oligarch Rinat Akhmetov paid $216 million for a penthouse in the complex. It’s the most expensive home ever sold.
Two apartments worth $43.7 million are owned by Professor Wong Wen Young, likely the Taiwanese business tycoon Winston Wong Wen Young.
In April 2011, Australian pop star Kylie Minogue dropped $25 million on a three-bedroom flat in the complex.
Mohammed Saud Sultan al-Qasimi, head of finance for the government of Sharjah, part of the UAE, reportedly paid $18 million for his apartment.
At least one apartment is owned by Russian real-estate tycoon Vladislav Doronin, who is dating supermodel Naomi Campbell.
Nigerian billionaire Folorunsho Alakija is believed to have spent $123 million on several apartments there, all supposedly registered under the name Rose of Sharon.
Vladimir Kim, a copper baron and the wealthiest man in Kazakhstan with a net worth of $2.3 billion, also owns a home there.
And Rory Carvill, an insurance entrepreneur and chairman of U.K. based R.K. Carvill & Co. Ltd. reportedly paid $33.5 million for his residence and additional storage space.
Two apartments held by Irina Viktorovna Kharitonina and Viktor Kharitonin, presumed to be a co-owner of Russia’s largest domestic drugmaker, cost $49.8 million.
Want to live in One Hyde Park? You’re in luck—a 5-bedroom flat there recently came on the market. At $101 million, it’s the most expensive apartment currently for sale in London.
Photos are of apartments currently for sale at One Hyde Park; not actual residences.
Thursday, May 24, 2012
JUST LIKE A HEATWAVE
Condo pace picks up steam in city
By Claire Young
Calgary Herald May 18, 2012
Compared to the last three months of 2011, resale condos sold faster from Jan. 1 to the end of March in three of four quadrants of the city, says the Calgary Real Estate Board.
All of the board’s zones except for Zone A — which roughly corresponds to the city’s northwest — sold more quickly than during October to December.
In Zone A, condos took an average of 58 days to sell — three more than during the last quarter.
Condos in Zone B, which roughly consists of northeast Calgary, averaged 58 days on market, down from 64 in the first quarter.
Meanwhile, Zone C — roughly southwest Calgary — saw the hottest sales with an average of 49 days on market, down from 60.
And Zone D, which is roughly consists of southeast Calgary, saw a six-day drop to an average of 50 days on market.
The new year brought many more listings for condos.
From Jan. 1 to the end of March, there were 2,702 new listings in the city compared with 1,644 during October to December.
The bulk of the new listings were in Zone C, with 1,492 added. This zone also saw the most sales at 783, up again from last quarter’s 612.
The only neighbourhood to hit triple-digit sales in 2012’s first quarter was Connaught in Zone C, which saw a tidy 100 sales averaging $309,451.
Other neighbourhoods in Zone C that sold well were Victoria Park with 48 sales averaging $351,754, and Bankview with 32 sales averaging $262,512.
The most expensive neighbourhood from Jan. 1 to the end of March was Varsity Estates in Zone A, which had two sales averaging $598,750.
The most affordable neighbourhood was also in Zone A — Highland Park, which had one sale for $79,000.
During the first three months of 2012, the average sale price increased in all zones except Zone D — where this quarter’s average sale of $259,768 marked a decline from last quarter’s $268,998.
Zone C had the highest average sales at $307,822, an increase from $298,960.
Zone A’s average sale was $281,193, up almost $10,000, while Zone B was up a little more than $4,000, with an average sale of $173,544.
Labels:
2012,
Calgary Real Estate Board,
Christina Hagerty,
Condo,
CREB,
Downtown,
ZONE A,
Zone B,
Zone C,
Zone D
Friday, April 27, 2012
BLOOM & BOOM
Calgary housing market booming
Calgary Herald April 23, 2012
Just over three weeks into April and it appears Calgary’s housing market has seen a resurgence of activity this spring.
A boom perhaps?
According to the Calgary Real Estate Board, MLS sales in all housing categories are noticeably up compared with last year.
From April 1-22, single-family sales of 1,108 transactions are up 26.05 per cent from the same period a year ago but the average sale price has dipped by 0.43 per cent to $481,423.
The condo apartment category has seen sales grow year-over-year by 14.91 per cent to 262 units while the average price has dropped by 2.83 per cent to $269,046.
And in the condo townhouse sector, sales of 198 are up 15.79 per cent from last year and the average price has risen by 6.46 per cent to $319,140.
Friday, November 25, 2011
A NOTABLE MENTION!
GTA condo sales this year smash record
Garry Marr
Financial Post Nov 22, 2011
Condominium sales are taking over the Greater Toronto Area new housing market and some parts of the country are following closely behind as rising costs push consumers into vertical housing, a new report suggests.
The Building Industry and Land Development Association said there were 23,747 condo sales in the Greater Toronto Area through the first 10 months of the year, smashing the previous high of 22,316 in 2007 — with two months yet to go.
High-rise sales accounted for approximately 61% of all sales in GTA from January-October. At this point last year high-rise sales only accounted for 57% of the overall market.
“It’s very much becoming a condo market,” said Joe Vaccaro, acting president of BILD. “Ten years ago the split was 25% high-rise versus 75% low-rise.”
The trend appears contained not just to Toronto’s urban core but is now moving to the suburbs. “There seems to be a new trend setting in over the last couple of months with the 905 [suburban] areas outperforming Toronto when it comes to [condo] sales,” said Mr. Vaccaro.
Suburban land costs have skyrocketed because of what the industry refers to as regulatory inertia with no new land developments approved in the suburbs over the last five years. It has led to the hoarding of land and rising prices for single detached homes.
A report Tuesday from Altus Group suggests the GTA will not see any sort of slowdown in new condo construction in 2012.
“New condominium apartment sales in Toronto and Ottawa continue to hum along, which will continue to buoy apartment starts in Ontario through 2012,” said Altus.
Peter Norman, chief economist for the Altus Group, says population growth has supported the Toronto condominium market. “That number of people generates a fair amount of housing demand no matter what is happening,” says Mr. Norman. “Add in the interest rate environment, and them not going up, and that adds to it. There has been a restriction on [new] lots and a lot of people have been shoved into apartments.”
The group looked at 10 real estate markets across the country and found only Alberta is set to rise in 2012. Regina, along with Toronto, is forecast for flat sales.
“Calgary and Edmonton employment growth in 2011 has more than made up for 2010’s declines,” says Altus. “Although employment growth will be more moderate in 2012, the strong showing this year is favourable for stronger housing starts in 2012.”
Altus is forecasting apartment starts to jump to 5,475 in 2012, up from 3,975 in 2011. Single family construction is also forecast to jump to 22,325 in 2012 from 20,906, putting high-rise construction at almost 20% of the Alberta market.
Phil Soper, chief executive of Royal LePage Real Estate Services Inc., says his company has noticed the trend in top condominium apartments in its corporate owned franchises in Toronto and Vancouver. “There is the cost of the commute, the hard costs like gas and insurance but then there is the soft costs in time,” he said, noting consumers look for housing that is closer to subways and urban cores.
If anything, he says Canadian cities, including Toronto, are playing catchup when it comes to high-rise construction. “Look at big established mature cities like New York. They have much more vertical living per resident than we do, they just don’t have as much on per capita basis that is new,” says Mr. Soper. “We have hundred of thousands of new Canadians that have to be accommodated in Toronto.”
Photo By: Surrealplaces
Friday, November 18, 2011
THE 411 ON T.O. CONDOS
Cool with condo
Alex Newman
National Post Nov. 18, 2011
As Toronto condo prices march steadily upward, luxury suites are right in step. Fetching at least $1,000 per square foot with sizes anywhere from 1,800 to 4,000 sq. ft., final sale prices are well into the millions. Not surprisingly, such projects are situated in the city's toniest neighbourhoods - Forest Hill, Yorkville, Yonge and St. Clair, the financial district, plus a smattering along the waterfront.
What is surprising, however, is who is buying. In addition to the wealthy couple downsizing from their large family home, and foreign investors looking for a safe financial haven, there's a newly emerging group of younger buyers.
What's even more surprising is that a sizable number of them are first-time buyers, according to Tina Amato, vice-president at Baker Realty, which handles sales for the Ritz-Carlton. Given that suites start at $1.4-million, these younger buyers are clearly well employed. Because most are single and work long hours, they love to be able to walk to work through the PATH system, and love the hotel perks such as maid or room service, she says.
As much as they like to be pampered in exchange for the gruelling schedules, Ms. Amato says they're also realistic about spending: "If they can't manage the Ritz, they'll go the next project down, which may not be the Ritz, but is still luxury." Stephen Price, COO of Graywood Developments, which built the Ritz-Carlton, says 10 years ago "that group wouldn't have existed in a project of this nature."
A similar shift is apparent at Trump Toronto. "Early on, the bulk of our purchasers were a mix of Canadian and foreign investors," says Howard Tikka, director of marketing for Trump. As the tower nears completion, however, he is finding more local people, some empty nesters but particularly area finance workers who want to have a downtown residence. It's also attracted companies looking for guest suites for clients who come to Toronto on business.
A similar story unfolds at the Shangri-La - a 66-storey, 370-unit project described by its marketing manager Michael Braun as being at the "intersection of the cultural entertainment and business worlds." Situated at University and Adelaide, with suites ranging from $1-million to $13.3-million for a 6,700-sq.-ft. two-storey penthouse, it's attracting whiz kids who work in the financial district and are buying up some of the smaller suites.
Even empty nesters seem to be younger downtown. Mr Braun notes that a number of buyers aged 40 to 55, not yet retired but with older kids who are moving out, "want the action of downtown." Call it a condo mid-life crisis, if you will.
While the downtown buyer wants a hip location, the downsizing older couple craves a luxury spot in familiar territory: midtown or north Toronto where they've owned large family homes. They end up choosing suites in projects like The Four Seasons, Museum House and The Avenue.
"Buyers in a downsizing phase still want to stay in the community where they have always lived," says Elli Davis, a top Royal LePage agent for luxury residential resale. "They want to be able to walk to Forest Hill Village, take a quick streetcar ride to Yonge and St. Clair, be near the subway."
Those buyers are the majority of Hunter Milborne's clientele, as well. As managing partner of Sotheby's, he's sold some of the city's most expensive condos to people from "higher-end neighbourhoods, like Bayview, Forest Hill and the Kingsway. And most are independently wealthy."
The suites they buy - for anywhere from $1-million to $10-million - aren't even a "huge part of their net worth," Mr. Milborne says. One couple, who couldn't decide which apartment to buy, purchased both, figuring they'd sell whichever one they decided not to keep.
And what this market wants more than anything is space, says Mimi Ng, vice-president for Menkes, which developed the Four Seasons. "Our purchasers are primarily end users who are either downsizing from a family home, or already living in a condo and making the move to a larger suite in a new building," she explains.
The other draw is service, which could put hotel-condos in the front of the luxury pack. "A big part of buying into the [Four Seasons] is its reputation for incredible personalized service, and access to all those amenities, concierge, spa, restaurant," Ms. Ng says.
The final group of luxury buyers is international. "International buyers represent about a third of the suite sales at Shangri-La," Mr. Braun says. He figures these buyers probably have business interests in the city, and tend to travel from home to home.
Trump Toronto also has its share of the international market. Mr. Tikka says their buyers come from the U.K., the U.S. and 20 other countries. While Canadians account for about 35% of Trump purchasers, U.K. buyers represent about 25% and U.S. about 20%. The remaining 20% are scattered throughout the world.
The waterfront is a big draw for the international buyer, says Cityzen Group's president Sam Crignano. His Pier 27 project has a wide variety of suite prices, but luxury purchasers are attracted to the penthouse suites, which command about $1,000 per square foot.
Mr. Crignano has recently noticed an increasing interest "from wealthy buyers from mainland China and south Asia," he says. "They may want to live in the suite, but mostly they want to park money with the reassurance that if there's political upheaval where they're from, there's a place they can go to."
Foreign buyers have always gravitated to waterfront properties, Mr. Crignano says. "[It's a trend] that's not just here but elsewhere in the world, because there's a perception that waterfront projects demand a higher-per-square-foot price."
While location and suite size are major factors in luxury purchases, suite finishes are a close second. These include marble bathrooms, 10-or 12foot ceilings, top-of-the-line fixtures and kitchen cabinetry and appliance packages featuring Sub-Zero, Wolf or Miele. Other draws: soaker tubs and rainshower sprays and saunas and private elevators, also real hardwood floors (as opposed to engineered hardwood), granite, marble or limestone tiles, plaster cornice mouldings, and eight-inch baseboards.
Amenity spaces are also lar-ger and more luxurious. The city's usual requirement of two square metres of amenity space per unit won't do in a luxury building. For one thing, units are typically large, so there are fewer per building, which makes amenity space smaller than any mid-market building.
The pampering quotient of amenities is nice, especially when they include spas and such, but they're as much about increasing a resident's overall living space. A 1,000sq.-ft. condo in the Trump Tower, for example, expands exponentially to include housekeeping and room service, a two-level full-service spa and wellness facility, and a 10,000-sq.-ft. business facility.
Naturally, maintenance fees reflect these benefits, with high-end projects levying $1 per sq. ft. "What creates cost is staff," Mr. Milborne says. "Valet parking, concierge, spa manager that all translates into high maintenance fees."
About 8% of the condobuying public qualifies for a luxury product. What's financing this choice, at least in the downsizing set, says Ms. Davis, is the fact that they own large homes that have appreciated wildly since first purchased. Simultaneously, there's a "transfer of funds coming down the generations."
They've got the money, but they're ready to shed responsibility, Ms. Davis says. They're trading the high-maintenance large home for the freewheeling condo lifestyle. But with few options in familiar neighbourhoods - close to the shops and cafés they're attached to - developers have had to find land, even if it's on the fringes of established single-family neighbourhoods. 1717 Avenue Road - the first condo project in that whole area - for example has attracted three of Ms. Davis's empty nester clients.
Although the price tags on luxury suites can run as high as $10-million, Ms. Amato says Toronto is still "cheap" in the world market: "Our prices are lower than any other large city in the world, including Vancouver. The Ritz, at $1,100 per sq. ft. for example, is a lot lower than New York where I'd say it's at least $4,000 per sq. ft. for something super luxury."
Which is to say, luxury could be considered a bargain in this city.
Thursday, September 22, 2011
BUYERS LURED!
More buyers attracted to city's condo market
By Mario Toneguzzi
Calgary Herald September 20, 2011
Two high-profile projects will launch into the next phases of their development this weekend, suggesting the city may be poised for a residential condo rebound.
Keynote Urban Village will open its doors to a new show suite for its second tower in the east Beltline area while University City will launch its Building 3 project near the Brentwood LRT Station.
"Activity in the condo market has been gradually improving," said Richard Cho, senior market analyst in Calgary for Canada Mortgage and Housing Corp.
"Gains in employment, favourable mortgage rates, and price reductions have attracted buyers to the condo market, especially those looking for their first place."
A majority of Calgary condo sales this year have been for units priced below $300,000, said Cho, who expects to see more apartment-type condos break ground in the coming months. "There has been an uptick in the number of apartment permits issued, signalling the intention of more activity," he said.
According to CMHC figures, the 451 apartment starts in August was the highest monthly total since May 2008.
The 29-storey second Keynote residential tower will include 250 suites.
Possessions are scheduled for summer 2013.
Project sales manager Jeannie Elrafie said sales have been surging during the past eight months and that's "telling us there is an upswing underway in the Calgary real-estate market".
"We're getting a lot more demand than we ever were," she said.
The Keynote development, which encompasses nearly an entire city block on 1st Street S.E., already includes a 26-storey residential tower comprising 179 units, and a 14-storey office tower that includes 40,000 square feet of retail space, occupied by the likes of Sunterra Market, Starbucks, and an RBC Royal Bank branch.
The city's subdivision and development appeal board last week approved construction of the first two condo highrises for the University City project.
An invitation for this weekend's VIP launch of the third building says 400 condos sold in five days for the project's first two buildings.
A public launch is expected to be announced next week.
The first two towers are 18-storeys, each with 216 units.
The University City website states the project's third and fourth phases will consist of 12-to 14-storey buildings.
The planned fifth phase will be four storeys.
Labels:
Calgary,
Calgary Real Estate Blog,
Christina Hagerty,
Condo,
Condo Sales,
Keynote
Monday, September 19, 2011
THE SIMPLE LIFE
Small, simple, smart
By Pedro Arrais
National Post · Sept. 16, 2011
The combination of an aging population, first-time buyers and rising real estate costs has created the trend toward downsized living areas, with the resulting challenge of how to do more with less.
Smaller rooms have folks rethinking their furniture needs. Disposing of some items is an option, but the solution many people are turning to is multi-functional furniture.
Some pieces have long been multifunctional. In many homes, a dining room chair is moved to another room - a home office, for example - to serve as an occasional chair until needed for large dinner parties.
In many households, the dining table functions as a task desk by the family before and after dinner.
"People expect their furniture to do more," says Dana Wright, merchandising manager for La-Z-Boy Furniture. "They are looking for a simpler life."
She says the trend toward multi-functional furniture began when home sizes began to get smaller. Interior changes, such as a move away from separate living and family rooms to a great room in houses, created a need to reduce visual clutter.
Nowadays, ottomans invariably double as storage bins, and coffee tables have drawers for remotes and magazines.
"It is an ongoing evolution," Ms. Wright says. "At one time there was only a television to contend with. Now we have large flatscreen televisions and gaming consoles. All those components and controllers need to be hidden away."
It is easier to adapt to small living spaces if the furniture is smaller as well. An average sofa is about 216 centimetres long. A condo-size sofa can be 198 centimetres.
"Manufacturers typically put straight and narrow armrests instead of wider, more traditional rests on condo-size couches. That makes the difference in width not that noticeable but it fits better in smaller spaces," says Love Dodd of Dodd's Furniture in Victoria. "Some bottoms flip up to reveal storage underneath, some have a chaise on one end and others can recline. It is all about catering to different needs."
Even the traditional sofa bed, the original multi-functional piece of modern furniture, has evolved.
"Our hide-a-bed couch separates into two chairs, which can face each other, turn and swivel," says Chris Morton, assistant manager at Nood Furniture, a chain of stores in Western Canada. "We carry furniture with more European sizing, with smaller dining chairs and slipper chairs with no arms."
Also in an effort to declutter, people are looking for elegant solutions to recharging their electronic devices. Complex docking stations with hidden power bars are now built into bedroom night stands or kitchen sideboards.
Furniture is not the only item that is being asked to do more. Increasingly, interior designers are also being tasked with coming up with multipurpose rooms.
"It comes up all the time," says Cydney Hellier Gray, principal of an interior design business that bears her name in Victoria. "The classic scenario is for a condo's only extra room to be a TV room, a den, an office and a guest room when called upon."
She advises people to build more custom cabinetry to take advantage of dead space in a room. But she also warns multi-functional pieces should be used in proportion to a room's dimensions.
"I am not a fan of wall beds," she says. "They tend to make a room look smaller because of their bulk." She tries to keep furniture less than 91 cm in height because it visually preserves a sense of volume in a room when a person can see the wall. Any higher and that piece dominates the room because it eats up a person's sight lines and makes a small room look smaller. She says Murphy beds work better in larger spaces.
"It all comes down to a sense of balance and proportion." PH
Tuesday, September 13, 2011
THEN THERE WERE TWO...BUT IN THE MEANTIME...
Home buying help for singles
By Helen Morris
National Post
Purchasing a home alone can be daunting but help is at hand to make the most of your single income.
"Get pre-approved -with a single income, many times people are looking at condominiums. The condo fees and taxes need to be included, and, of course, the mortgage payment," says Kevin Suddaby a mortgage broker with Invis in Calgary. "Make sure you've got a complete assessment of what you can afford. Get an interest rate held, so that you are protected while you are looking for a home."
The new mortgage rules effective March 18 need consideration.
"We don't have access to the 35-year amortization anymore. This is impacting singles more than couples who have dual incomes," Mr. Suddaby says. "You can qualify for less property now."
One option may be to ask a co-signer, such as a parent, to help you qualify for the mortgage.
"By co-signing or guaranteeing the debt the parent is obligated as much as their son or daughter with the payments," says Stan Falkowski, senior vice-president, Mortgage Intelligence in Toronto. Helping with the down payment may make more sense.
"We're looking at the baby boomers. Their kids are now buying homes. If parents can afford it and they have assets, it wouldn't be a bad time to gift a down payment," Mr. Falkowski says.
With only your income under consideration, putting together a healthy deposit is more important than ever.
"For those who are looking to buy in the next two or three years, it's a good point to max out on their RRSPs every year if they can," Mr. Falkowski says.
"They can in turn use those funds for the down payment."
If you meet the Canada Revenue Agency criteria as a first-time buyer, you can withdraw up to $25,000 from RRSPs to buy or build a qualifying home. Mr. Suddaby says you may also borrow funds to put into an RRSP and then withdraw those after 90 days to generate a down payment.
"The borrowed loan affects your total debt service," Mr. Suddaby says. "If you contributed to an RRSP earlier this year, there's a chance you would get a tax refund that can also be used as a down payment."
If you are receiving child or spousal support, these can count as income. Mr. Suddaby says many clients come to him too soon after they become single. The separation must be legally documented and the lender needs to see a clear record of payments. Mr. Suddaby says a home with a separate rental unit can generate more income, but it is critical to get good advice on all the expenses involved and work out if the additional time and effort is worth it. If you do not qualify now Mr. Falkowski says don't give up, have a plan.
"If they take a look at their financial situation: They can't get a gifted down payment; their RRSPs are a little low; it's never too late as long as they put a plan in action," Mr. Falkowski says. " 'With what I can put away, I can buy a place in two, three years or whatever.' In the time frame that they're actually starting to save they could meet someone and they could start saving together."
APARTMENT SALES ENLARGEMENT
Mondo condo sales for 2011
Lisa Van De Ven,
National Post, Sept. 10, 2011
If you ask Ben Myers, 25,000 is the magic number. There may still be a few months left of 2011, but Mr. Myers, executive vicepresident and editor at real estate research firm Urbanation, already has his forecast for the year. He expects there will be 25,000 new condominium sales by the end of 2011. If he's right, it'll be a new record, surpassing 2007's previous record of about 22,500 new condo sales.
"We're certainly on pace to have the most condominium sales in any one year in 2011," Mr. Myers says. And with the Toronto new-condo market coming off a busier-than-normal summer and a record-setting second quarter, he's not surprised.
Urbanation recently released its second-quarter results. From April to June, Mr. Myers says, 9,455 new condo units were sold in the Toronto CMA. That's a record in itself; the previous best quarter was 2007's second quarter, when 6,997 units were sold. That wasn't the only Q2 number to be beat, though. The quarter also set records for the number of active projects, the number of active units, the number of new condominium launches and the number of projects and units under construction.
"There was a huge number of new projects coming on line," Mr. Myers says. "And surprisingly, even with all of this extra supply, they had the highest absorption rate ever of new product. Even in the face of all this additional supply, they sold better than any other new release that we had in a quarter."
But Mr. Myers is quick to dispel any talk that the Toronto market might be in the middle of a real estate bubble. Prices, he says, have remained "pretty consistent" over the past five years, with 7% to 9% increases in the new condo market from year to year.
"A bubble is characterized by rapid increases in prices, and we haven't seen that," he says. "That's the type of thing you obviously saw in the United States and you even saw in Calgary a few years ago, where you saw 20% and 25% increases year over year, and in our market in the '80s where we saw prices double in three years."
Developers, he says, have been doing their homework and "setting fairly moderate pricing." They're also, it seems, paying less attention to the sales seasons of the past. Whereas spring and fall are still the prime selling times, more developers decided to release their projects in the summer this year. Since the market is being driven by investors more than ever, Mr. Myers says, there was less need to wait out the summer season, when end users are typically on holiday and less focused on condo buying.
According to the Building Industry and Land Development Association (BILD, using data provided by RealNet Canada), 1,490 new condo units were sold throughout the Greater Toronto Area in July, up almost 20% from last year. "Forget the old conventions of a spring and fall market," says Stephen Dupuis, BILD's president and CEO. "The market's that much bigger now - it's active all the time."
Photo By: GalleryLoftsCA
Monday, August 8, 2011
GOTTEN GAINS
Condo market gains strength
By Kathy McCormick, Calgary Herald
August 6, 2011
The story of the resale condo market in Calgary is positive, albeit fragile, say some of the city's realtors.
For the first time since April 2010, sales of resale condos have gone up year-overyear - and in terms of new condos, several inner-city highrise projects that were in limbo have been brought back to the market.
For April 1 to the end of June, sales of resale condos reached 1,617 within the city.
The Calgary Real Estate Board's Zone C - which roughly corresponds to the city's southwest and includes the Beltline - posted the most sales from April 1 to the end of June at 881.
Not surprisingly, the busiest communities during that period were in the innercity neighbourhoods of Connaught with 95 sales and Victoria Park with 50 sales.
"Condo sales bounced back this month (in July) and we now have less than four months of supply on the market," says Sano Stante, president of the Calgary Real Estate Board. "Stronger condo sales, combined with a decline in inventory, will lend more balance to this market in the months to come."
The key, though, is prices, says Marlene Swinton of Real Estate Professionals Inc.
"Buyers today are extremely nervous and a lot of them come in well below list price," she says.
"A lot of sellers, on the other hand, haven't recognized that prices have changed. They don't want to hear that the marvellous prices they heard they could get for their place once isn't there anymore."
That resonates with Chris Zaharko of Royal LePage Foothills. "My gut feeling is that people are only in the position to buy and pursue it if they think it's the absolute bottom line."
Prices during the second quarter of the year averaged anywhere from $77,600 for five sales in Forest Lawn in the board's Zone B - which roughly corresponds to northeast Calgary - to $850,000 for one sale in Bayview in Zone C.
But overall, affordability was key. A total of 30 communities within Calgary had average sale prices under $200,000 - with more buyers purchasing condos under that price range this year compared to last year during the same period.
"Buyers in this market expect value and many are taking advantage of some affordable buys in both the single-family and condo markets," says Stante.
He expects this fall to be more active. "I think as the inventory is absorbed, more particularly in condos, the shift will be to sellers and there will be slight increases in price."
Swinton, who has a condo apartment building of 11 units among her portfolio of properties for sale, says she had three calls for showings for that development on the last weekend of Stampede - traditionally a very slow time for real estate transactions.
"It was priced well and a good product, but still, that is investors looking to buy, so that's positive."
Zaharko, too, points to the new condo market where several highrise developers are starting marketing or re-starting projects that had been on hold during the downturn in the inner city.
"The big developers are coming back to the table," he says.
"They've got their pulse on the market, and see what the oil and gas industry will be doing in the next couple of years. The timing is right to start now."
Typically, a highrise project can take two years or more for construction to be complete.
Zone C, which is mostly southwest Calgary and the inner-city neighbourhoods in the Beltline, was not surprisingly the most active for resale condos in the second quarter.
It also had the highest average price and highest median price at $317,301 and $285,000 respectively. The median price is the mid-point of all sales.
Overall, most condos took an average of 54.5 days to sell - but if it's the right product at the right price in the right location, it will sell quickly.
A $835,000 condo in Eagle Ridge in Zone C, for example, sold in just nine days during that period; another condo in Citadel in Zone A went for $440,000 in just four days.
Labels:
2011,
Calgary Real Estate Blog,
Christina Hagerty,
Condo,
Condominium,
Resale
Thursday, March 31, 2011
MOTIVATING MOVES
Making the switch to condo living
Financial security a major motivator behind the move
By Denise Deveau
For Postmedia News March 30, 2011
For Sara Kinnear, an investment firm lawyer in Winnipeg, moving from her house to a condo was the perfect way to simplify her life.
After three years of owning a detached home, she realized that the maintenance chores were more than this busy professional wanted to handle.
"There weren't any big problems, just the normal stuff around the house," she says.
"But having to arrange time to be at home to have people fix things and getting estimates .. It was too much of a drain on my time."
Condo living suits her lifestyle much better, she says.
"I like the fact everything is on one floor, it's on a better bus route and I don't have to have people look at the roof when it needs fixing," says Kinnear.
"Someone else will do that for me now. And I don't have to shovel snow when it's -40 C or mow the lawn when it's 30 C."
Kinnear is not alone in preferring the maintenance-free lifestyle that condominium living has to offer after experiencing the ups and downs of home ownership.
Jack Courtney, assistant vicepresident of advanced financial planning for Investors Group in Winnipeg, says he's seen the trend happening within many families, including his own.
"My in-laws sold their house to move to a condominium, not because it meant a cost savings but because it could give them more freedom to go to the lake and other things."
They made the move despite the fact they had a home with a pool that overlooked a golf course.
"He liked to golf, but didn't want to have to cut the grass or look after the pool anymore to do it," Courtney says.
Urban centres are seeing a growing influx of people moving back to condominiums after going through the life cycle of home ownership, confirms Andrew Bodnar, a sales representative with Re/Max Condos Plus in Toronto.
"Maintenance is a big reason or they simply kept a house to accommodate a family that has moved out. With condominiums, there's a lot of comfort, less stress and enough room and amenities for people to enjoy themselves."
Financial security is also a major motivator, he adds.
"We see people in different financial stages of savings who want to use the equity in their home to increase their cash flow later in life."
Courtney agrees the transition is often motivated by a need to free up capital for retirement.
If this is the intent however, he advises that prospective buyers make sure they understand all the expenses involved when making the move, from closing costs and commissions, to acquisition and maintenance fees.
A major consideration in making the switch from house to condominium is the nature and extent of the capital repair funding for the property you're considering.
"Sometimes capital repairs on a condominium property can be significant if there isn't a sinking fund in place," Courtney says.
"In fact, if you're looking at a property and the condo fees seem out of whack or too low, I would be suspicious and start asking questions."
Otherwise, you may get hit with a big assessment for a major repair to a parkade, for example.
"I knew of one property that was a converted highrise apartment block, where the tenants were stuck with a huge foundation repair issue and there was no fund put aside," he says.
The best defence for prospective owners is to examine the condominium owner's agreement carefully, Courtney advises.
"I would hope that a real estate agent dealing in condo sales would be familiar with the process," he says.
"A lawyer definitely should be. Have them review the terms and explain them so you have a better understanding of what you are getting into. Don't be afraid to ask, where is that $400 a month fee going and how is it used?"
When it comes to fees, Bodnar says it's relatively easy to manage them based on the available amenities.
"Most recognize there's a correlation between fees and amenities. You might have a couple looking to streamline expenses, so if they are concerned about costs, they may look at properties that have a smaller gym or don't have a pool."
He advises restraint for people on tight budgets who need to secure financing.
"A $100-a-month reduction could be the difference between getting that approval or not."
Subscribe to:
Posts (Atom)